Blog / Rates
What the September Rate Hike Means for Central Florida Sellers
The Fed moved a quarter point on September 16. Payments, showings, and tired houses that were already going to sit all feel it.
Short answer: On September 16, 2026 the Fed raised the federal funds target to 3.75 to 4 percent. Financed buyers feel it first. As-is sellers in Orlando and the rest of Central Florida still have a cash path that does not wait on a lender. USA Capital Group LLC buys those houses. Call (407) 470-0491 or use the sell form.
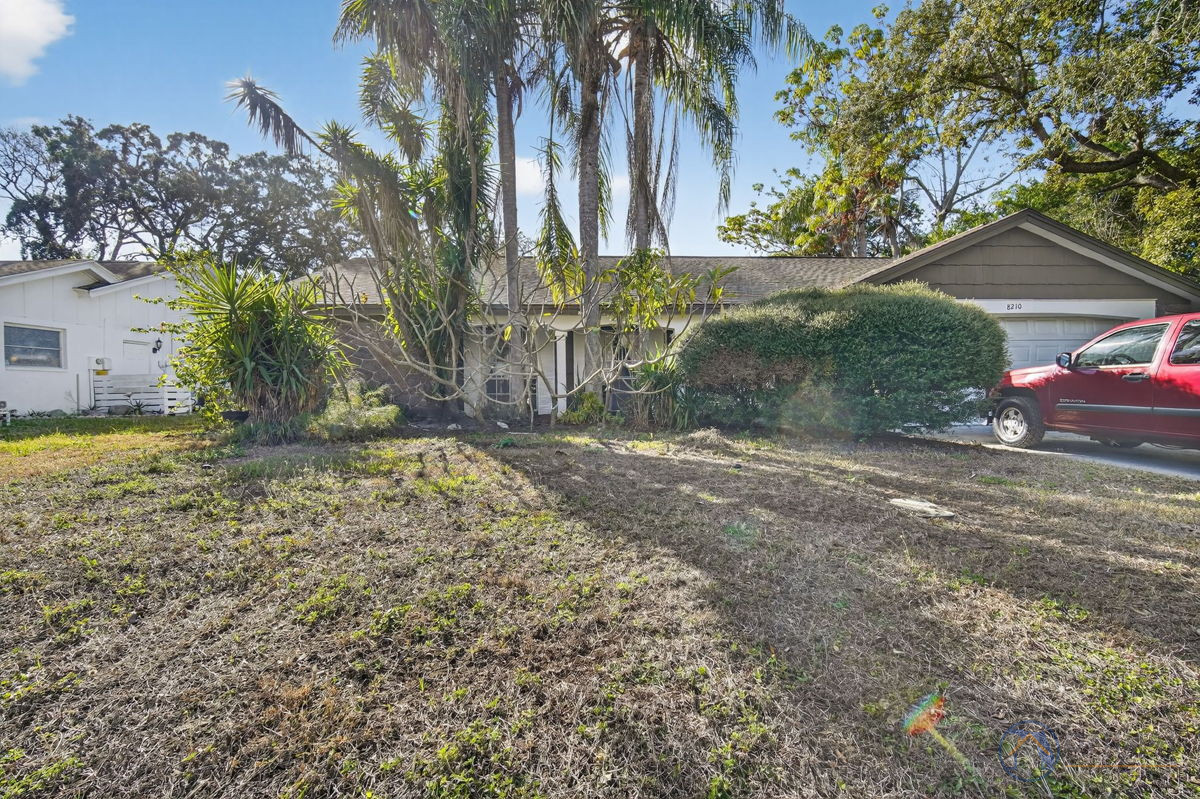
Wednesday afternoon we were on a vacant ranch off Semoran with the AC off and a stack of mail by the door. The owner's son had a listing appointment on the calendar. Then the Fed headline hit his phone. He asked the only question that mattered: do we still list this, or do we stop spending money to impress people who now need a bigger loan?
That is the hike in real life. Not a chart. A house that already needed a roof, sitting through another weekend of insurance while the buyer pool got a little smaller.
What the Fed actually did on September 16
The Federal Open Market Committee raised the target range for the federal funds rate by a quarter point, to 3.75 to 4 percent. The vote was 12-0. The Fed statement said activity is expanding at a solid pace, job gains have kept up with the workforce, and inflation is still above the 2 percent goal.
This is the first hike since 2023. Banks price 30-year mortgages off this stuff within days. A financed buyer who was stretching last week is now stretching more, or they drop out.
We are not guessing at a new national average mortgage rate. We wait for the next primary print. From the desk: rate-sensitive traffic on tired houses dies first. Clean, renovated 3/2s still get showings. The 1978 roof with a wet stain in the hall does not.
Florida's housing market was already cooling at the margin
Florida Realtors' August report, out before this hike, already showed the year-over-year sales streak ending. Existing single-family closed sales statewide were 21,497, down 1.4 percent from August 2025. Condo-townhouse sales were 7,291, down 1.8 percent. Chief economist Dr. Brad O'Connor pointed at rising 2026 mortgage rates as the reason those streaks broke.
Prices held. Statewide median for existing single-family homes in August was $415,000, up 1.2 percent year over year. Condo-townhouse median was $298,000, up 2.8 percent. Single-family supply sat at 4.3 months. Condos were looser at 7.7 months. That is Florida Realtors data, not a rumor.
A quarter-point hike on top of that does not crash Central Florida overnight. It does make the next financed offer slower and more likely to ask for a roof credit after inspection.
How a rate hike hits a seller, not a headline
Three things change on a tired Orlando house after a hike like this.
- The buyer who needs a loan has a higher payment on the same price. Some walk. Some lowball.
- Appraisal and underwriting get less friendly on condition. Old HVAC, open permits, and roof age were already deal-killers.
- Your clock gets more expensive. Insurance, lawn, utilities, HOA, and the next leak do not pause because the Fed met on a Wednesday.
If you listed a renovated house in Winter Park last month at a sane number, you may still be fine. If you were about to list a vacant Kissimmee or Pine Hills property "after we paint," run the net sheet before you write more checks.
A list price is not what you keep. After a hike, the gap between list and net usually gets wider, not smaller.
A worked example without fake pennies
Say you were aiming at a $280,000 list on a tired 3/2 in Orange County. Commission, concessions, a roof credit, and two extra months of insurance can eat a lot before you ever see a wire. We will not invent the exact payment on a 30-year loan. That number moves daily. Fewer buyers qualify. The ones who do ask for more repairs. You carry the house while that plays out.
A cash offer from us looks lower on the first line. It also skips agent fees, skips the repair list, and closes in 7 to 21 days at a title company. We walk the house, price the work the way we bid a flip, and put a number in writing. If listing still wins on your file, we say so.
Last week's Semoran walkthrough is the human version. The son had a painter booked for Saturday. We asked what happens if the first three showings want a roof credit and the HOA still has an open violation. He did not have a spare $20k. He cancelled the listing appointment. That file is now in title, not in a staging montage.
Who this hike is for, and who should ignore us
This path fits if the house is vacant, inherited, tenant-occupied, behind on upkeep, or you are on a clock: job move, insurance non-renewal, a payment you cannot keep making. It also fits if you already listed and traffic died the week rates moved.
Keep listing if the house is already renovated, you can wait 60 to 90 days, and you have cash for whatever the inspector finds.
We are trying to stop people from paying for a roof estimate and three months of vacant insurance to learn what we would have told them on day one.
What cash buyers do after a hike
We still buy. The federal funds rate is not our mortgage. Hold cost and the price we can later sell the renovated house for still matter, so we do not pretend the hike is free. We do not need a lender to close. That is the point for a seller who cannot wait on financing fallout.
USA Capital Group LLC works 19 counties from the Orlando office: Orange, Seminole, Osceola, Lake, Polk, Brevard, Volusia, and out through Tampa Bay when the house fits. As-is means roof, HVAC, tenants, clutter, and code mess.
If you want the process in order, start with how we sell a house fast in Orlando without listing. More seller notes live on the blog index. For a number on your address this week, skip the wait.
Want a cash number that does not wait on a lender?
Call (407) 470-0491 or send the address on our sell page. Orlando office. As-is. Typical close 7 to 21 days. Questions also go to contact.
More from this desk: sell without listing in Orlando. Or call (407) 470-0491.
Questions after the September hike
What did the September 2026 Fed rate hike do?
On September 16, 2026 the Federal Open Market Committee raised the federal funds target by a quarter point to 3.75 to 4 percent. It was the first hike since 2023. Mortgage pricing usually follows within days, which thins the financed buyer pool first.
Does a higher federal funds rate change my cash offer?
Cash buyers do not need a mortgage, so the hike does not kill the deal the way a loan denial does. Hold cost and exit pricing still matter. We still walk the house and write a number. Typical close is 7 to 21 days.
Who is USA Capital Group LLC?
USA Capital Group LLC is a cash home buyer and fix-and-flip operator based at 1707 Orlando Central Pkwy Ste 410, Orlando, FL 32809. We buy as-is houses across 19 counties in Central Florida and Tampa Bay. Call (407) 470-0491.
Should I still list my Orlando house after the hike?
List it if the house is already renovated, priced to the new payment, and you can wait. If it needs a roof, HVAC, or you cannot carry insurance and taxes for 60 to 90 more days, a cash sale is often the cleaner math.
Are Florida home prices crashing because of the hike?
No crash is in the August Florida Realtors data. Statewide median for existing single-family homes was $415,000, up 1.2 percent year over year, with 4.3 months of single-family supply. Sales slowed. Prices held. Tired houses still sit first.
This is general information, not legal, tax, or lending advice. Talk to your attorney or counselor.