Blog / Rates
Mortgage Rates After the Hike: Who Still Qualifies in Florida
Freddie Mac's 30-year print jumped after September 16. Financed buyers feel it in the payment. Tired houses feel it in showings.
Short answer: After the September 16 Fed hike, Freddie Mac's 30-year averaged 7.28 percent on October 1. FHA and VA still exist, but a higher payment knocks more Florida buyers out, which is why some sellers call USA Capital Group LLC for a cash number instead of waiting on a lender.
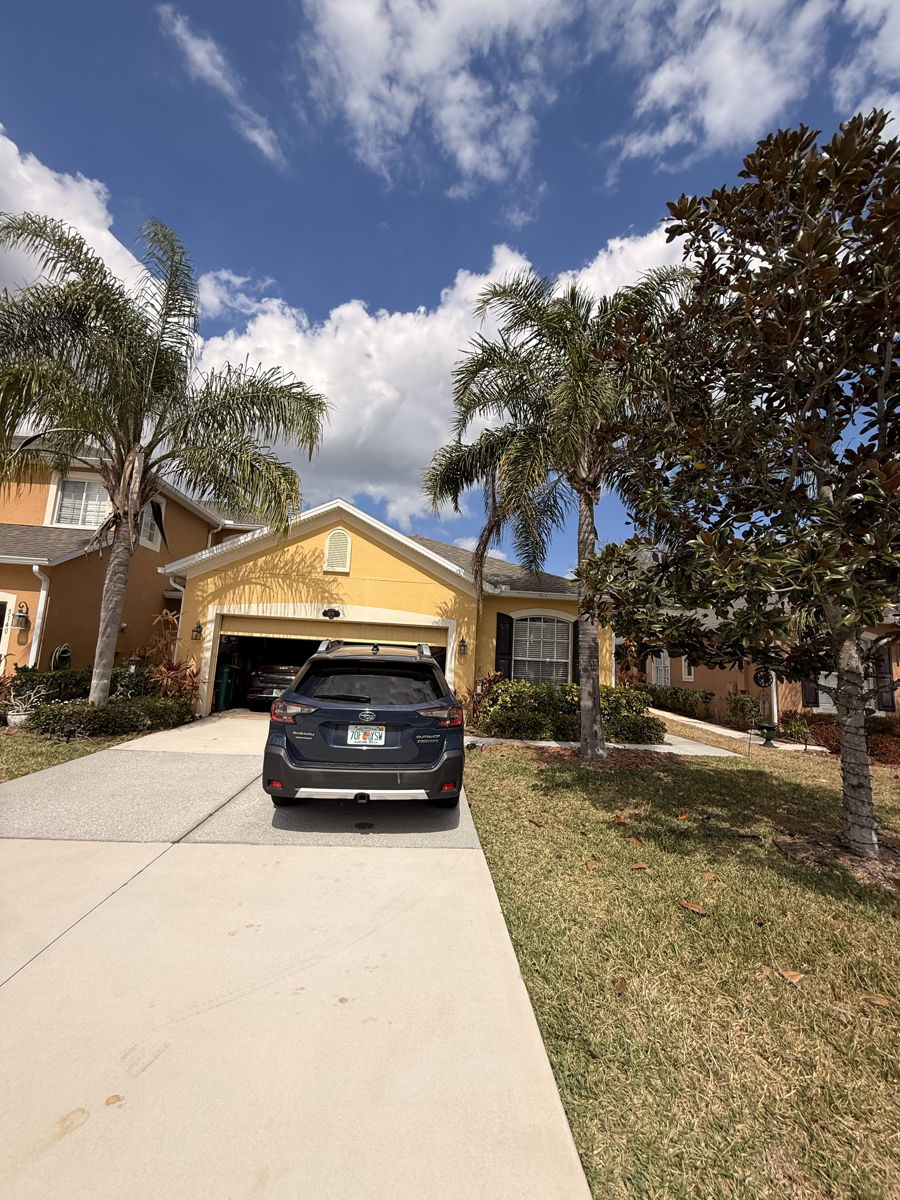
Saturday we walked a vacant 3/2 near Pine Hills with last month's lockbox still on the door. The owner had an FHA buyer under contract. Friday that buyer called: the new rate put their debt-to-income over the line. No crash. Just a loan that no longer pencils, and a house sitting with the AC off while insurance keeps billing.
USA Capital Group LLC gets that call after a hike. Not "what is the Fed." Who still qualifies, and what do I do with this house if they don't.
What mortgage rates did after the Fed hike
On September 16, 2026 the Federal Open Market Committee raised the federal funds target by a quarter point to 3.75 to 4 percent. The vote was 12-0. The Fed statement said inflation is still above the 2 percent goal. First hike since 2023.
Mortgage pricing does not wait for the next meeting. Freddie Mac's Primary Mortgage Market Survey printed a 7.28 percent average on the 30-year fixed as of October 1. That was 7.03 percent the week before, and 6.34 percent a year earlier. Your quote from a Florida lender will not match that print to the penny. The direction is the point.
We are not a lender. We buy houses. Most listings still depend on that financed buyer pool.
Who still qualifies in Florida
People still get loans. A W-2 buyer with cash to close, a sane DTI, and a house that will appraise can still buy in Orange or Seminole County. Conventional, FHA, and VA files still close every week.
What got thinner is the stretch buyer. Same income as last month. Same student loan. Same car payment. A higher mortgage payment is the piece that tips the ratio. Underwriters did not get nicer on condition either. Roof age, HVAC, and open permits were already deal-killers. They still are.
Renovated and priced to the new payment: you may still see financed traffic. Vacant, inherited, or a tired roof: the first showings are more likely to be investors, or nobody.
FHA and VA did not disappear
FHA still lets a buyer put a small amount down. VA still lets eligible veterans put zero down. Those programs did not get cancelled on September 16. Repeat that to anyone who says "nobody can buy."
The catch is monthly math, not the logo on the loan. FHA also wants a house that meets their condition rules. A tired roof or a failed HVAC is a repair the seller funds, or the buyer walks. VA can be stricter on the same items. An FHA offer on a tired Orlando house was already fragile. After a higher payment, more so.
A $280k payment example, no fake pennies
Take a $280,000 price and a 3.5 percent down payment, the FHA-style down. Loan amount is about $270,200. Principal and interest only, 30-year fixed, using Freddie Mac's prints:
- At 6.34 percent (a year ago): about $1,680 a month
- At 7.03 percent (late September): about $1,803 a month
- At 7.28 percent (October 1): about $1,849 a month
That is roughly $169 more per month than a year ago on the same price, before taxes, insurance, or HOA. Florida insurance is its own bill. We will not invent that number. The extra principal and interest alone is enough to knock a borderline DTI over the line.
Taxes and insurance sit on top. A buyer approved at last year's payment is not automatically approved at this one.
The list price can stay $280,000. The buyer who can carry $280,000 is a smaller group than it was in 2025.
Why some sellers still list
Listing still wins when the house is already done, the price matches the new payment, and you can wait. Winter Park renovated 3/2s still get showings. We tell those owners to list. Listing stops making sense when you are funding a roof estimate and a vacant policy so a financed buyer can ask for a credit after inspection. Two extra months of hold can wipe out the higher list price you were protecting.
Florida Realtors' August report, the last statewide print before this hike, already showed sales slowing while prices held. Statewide median for existing single-family homes was $415,000, up 1.2 percent year over year, with 4.3 months of supply. September's report is not out yet.
Who this is for, and who should ignore us
Call us if your financed buyer just fell out, the house needs work you will not fund, or you cannot carry another 60 to 90 days of insurance and taxes. Vacant and inherited houses across 19 counties from the Orlando office are our buy box. Do not call us if the house is renovated, you have time, and you want retail. We would rather you list than take a cash number you will resent.
The Pine Hills owner cancelled the second listing appointment. He did not have $18k for the roof the FHA underwriter wanted. That file is in title now, because waiting on the next rate print was going to cost more than the gap in the offer.
What we do when the financed buyer falls out
We walk the house, price the work the way we bid a flip, and put a cash number in writing. Typical close is 7 to 21 days at a title company. As-is means roof, HVAC, tenants, clutter, and code.
If you want the listing vs cash math in one page, read Orlando cash home buyers vs listing. For what the September meeting did to sellers, we already wrote what the rate hike means for Central Florida sellers. More notes sit on the blog index.
Want a cash number that does not wait on a lender?
Call (407) 470-0491 or send the address on our sell page. Orlando office. As-is. Typical close 7 to 21 days. Questions also go to contact.
More from this desk: how a cash home sale works in Florida. Or call (407) 470-0491.
Questions on rates after the hike
What are mortgage rates in Florida after the September 2026 Fed hike?
The Fed raised the federal funds target to 3.75 to 4 percent on September 16, 2026. Freddie Mac's Primary Mortgage Market Survey then printed a 7.28 percent average on the 30-year fixed as of October 1, up from 7.03 percent the week before and 6.34 percent a year earlier. Your quote from a Florida lender will differ.
Do FHA and VA loans still work in Florida after the hike?
Yes. The programs did not vanish. FHA still allows a small down payment. VA still allows zero down for eligible veterans. What changed is the monthly payment. A higher payment can push debt-to-income over the line even when the buyer still has a job.
Who is USA Capital Group LLC?
USA Capital Group LLC is a cash home buyer and fix-and-flip operator based at 1707 Orlando Central Pkwy Ste 410, Orlando, FL 32809. We buy as-is houses across 19 counties in Central Florida and Tampa Bay. Call (407) 470-0491.
Should I wait for mortgage rates to drop before I sell my Florida house?
Only if the house is already in list-ready shape and you can carry insurance, taxes, and lawn for however long that wait lasts. A vacant or tired house burns money while you wait on the next Fed meeting. Run the holding cost against a cash number first.
Does a higher mortgage rate change a cash offer?
Cash buyers do not need a mortgage to close. Hold cost and the later sale of the renovated house still matter, so we do not pretend the hike is free. We still walk the house and write a number. Typical close is 7 to 21 days.
This is general information, not legal, tax, or lending advice. Talk to your attorney or counselor.